A revenue gap is the difference between the result a business needs and the revenue its current opportunities can credibly produce. A large pipeline can hide that gap when value, timing or probability is weak. This guide turns the five-slide business note into a practical review with criteria, examples and safeguards.
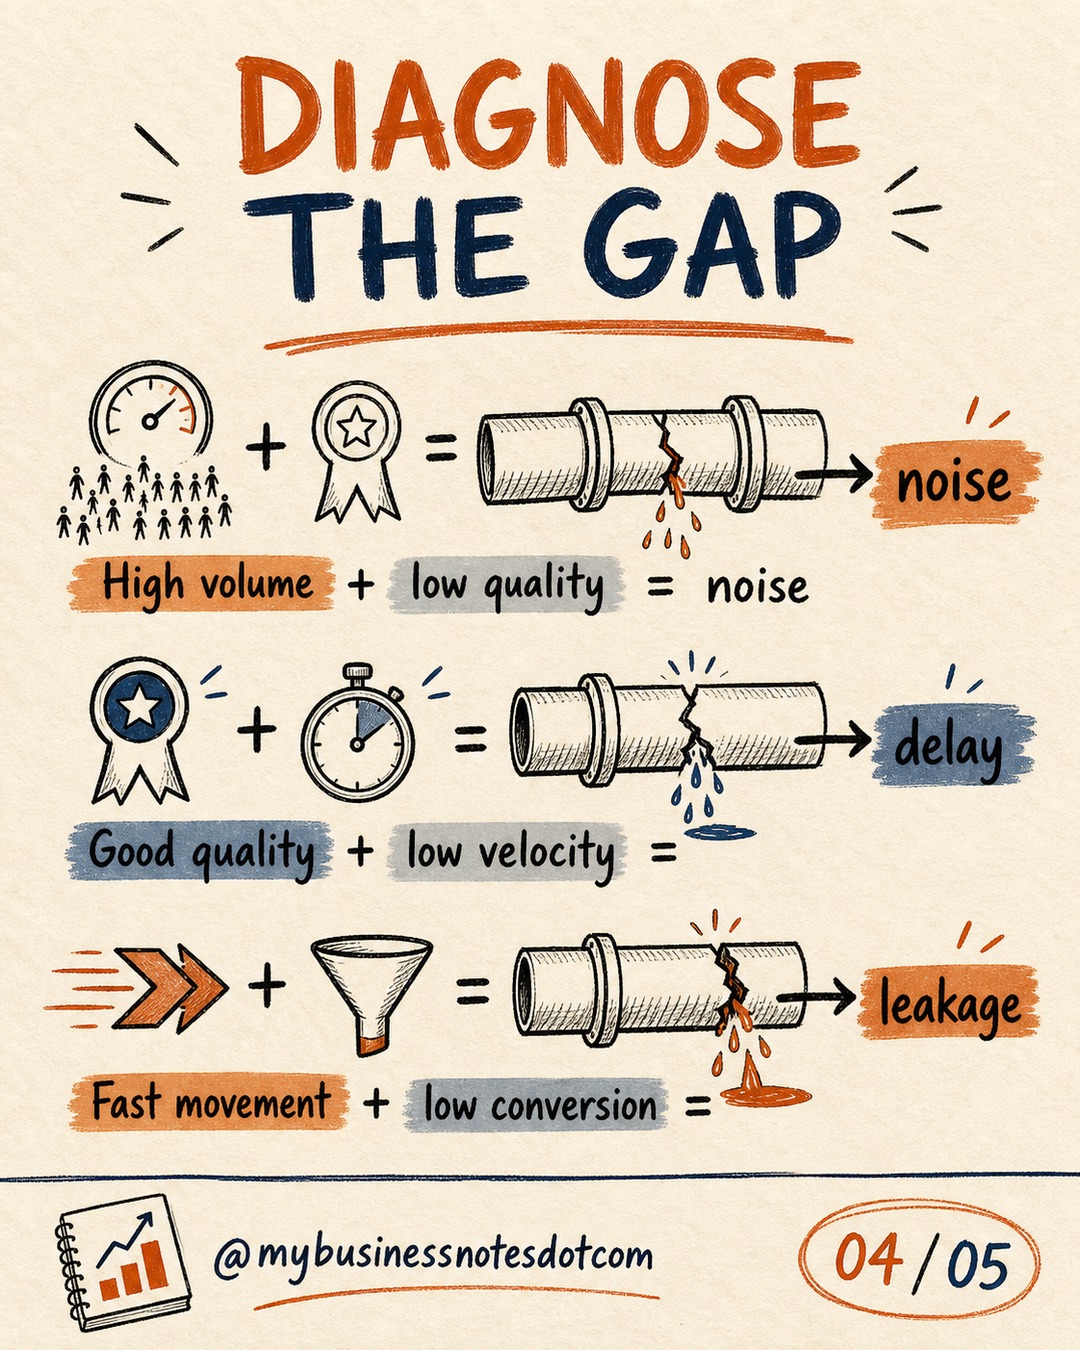
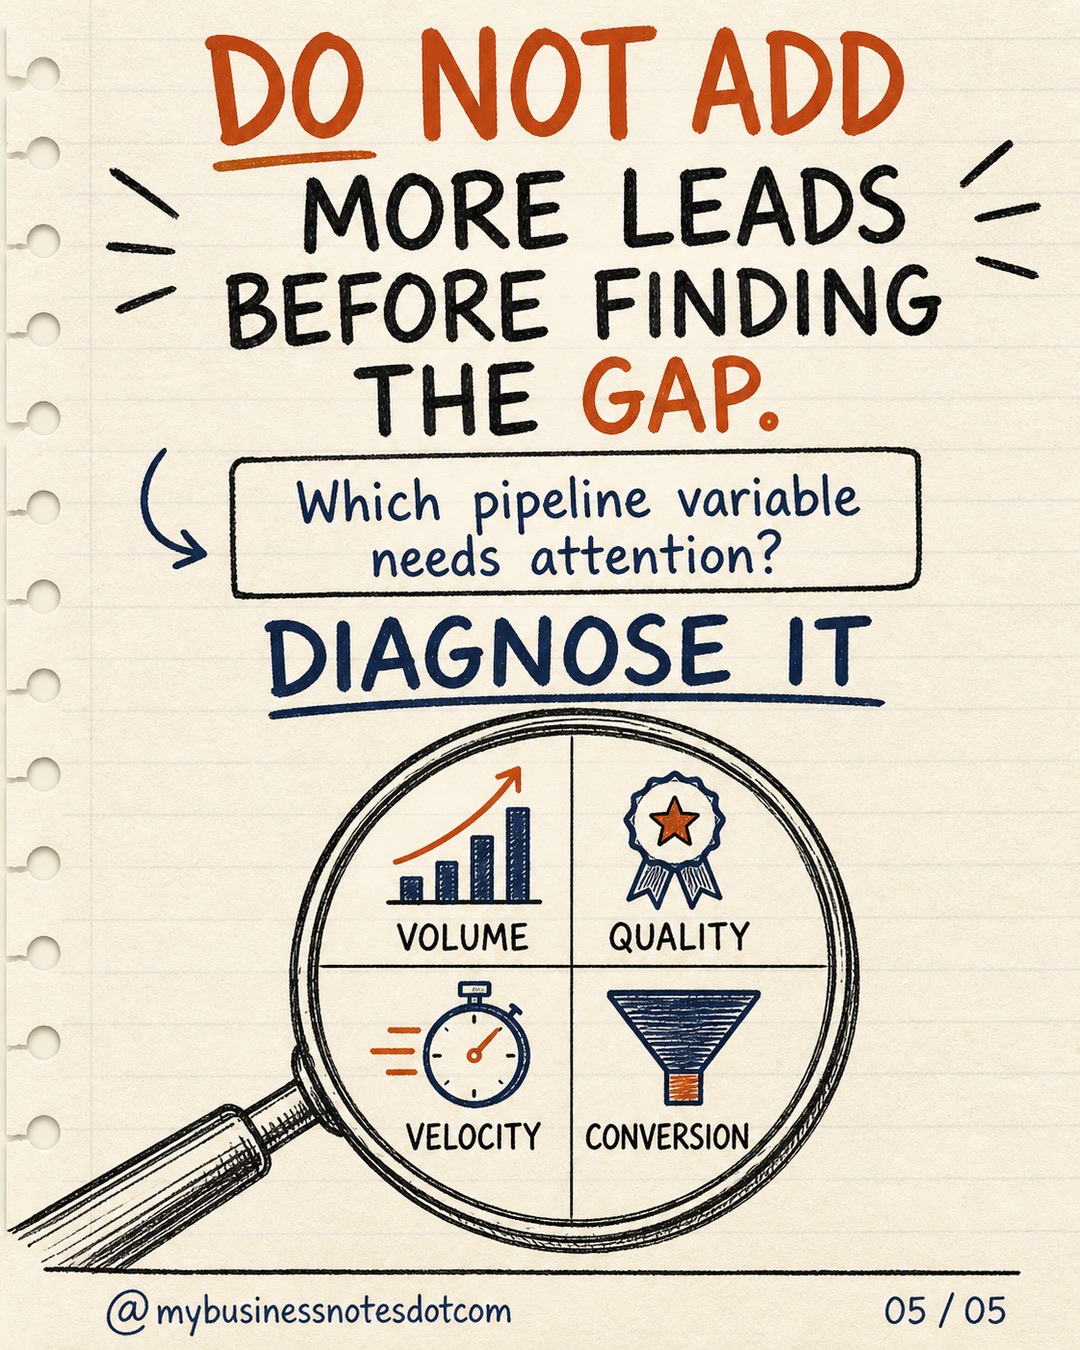
Slide 1 of 5
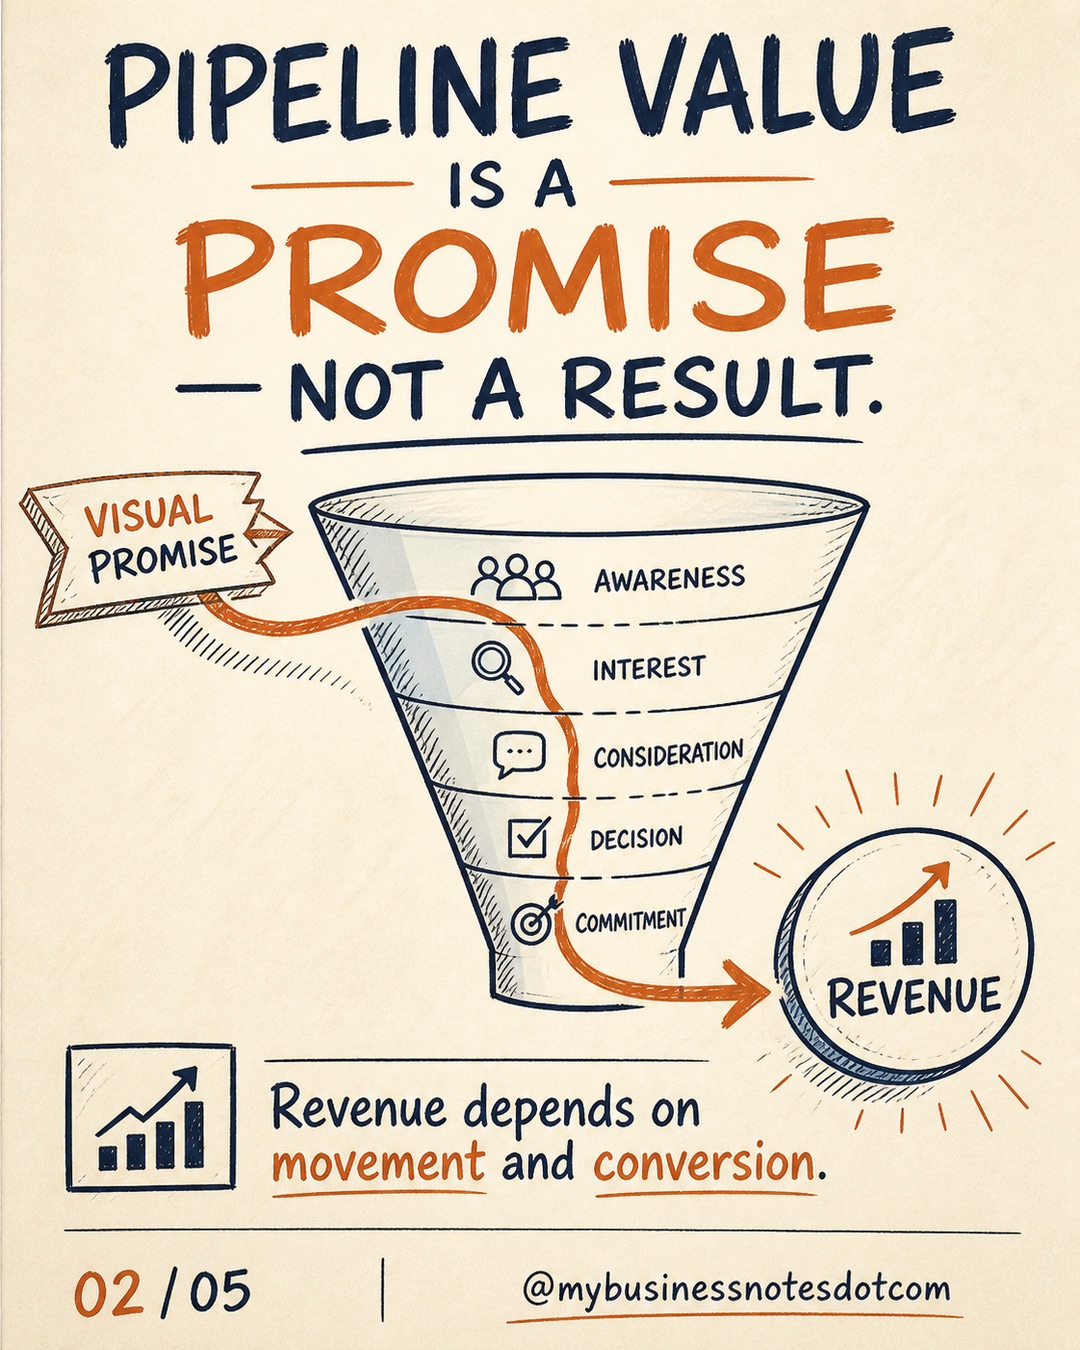
Pipeline value is not forecast value
Adding every open opportunity creates a reassuring number, but opportunities differ in quality and timing. A deal without verified need, decision access or a realistic date should not carry the same weight as evidence-backed work.
Rebuild the view from the target
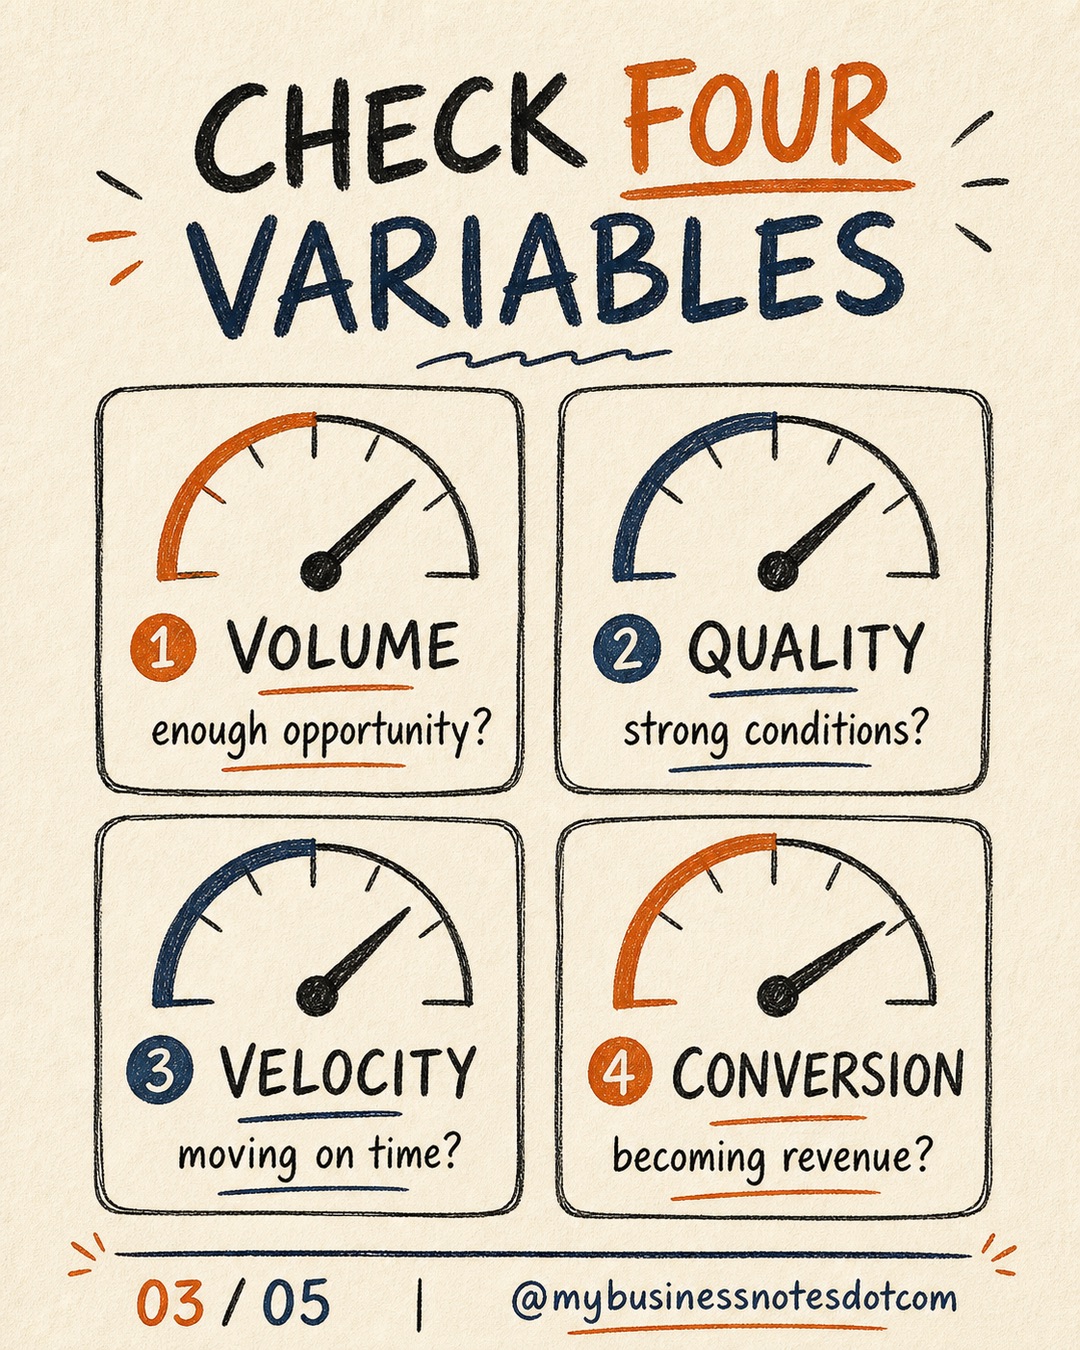
Start with the revenue required, subtract committed and highly credible revenue, then examine the remaining gap. Estimate how much qualified pipeline and conversion capacity are needed under explicit assumptions.
Check stage evidence
Define the customer evidence required for each stage. Movement should reflect a change in the buying process, not seller activity alone. Review stalled deals, repeatedly moved close dates and opportunities with one enthusiastic contact but no decision access.
Include timing and capacity
Revenue can miss the period even when a deal eventually closes. Consider implementation lead time, delivery constraints and recognition rules. A late, oversized opportunity may create concentration risk instead of solving the operating problem.
Choose a response early
The response may combine better qualification, expansion in existing accounts, faster offers, improved conversion or new demand. Make the assumptions visible and assign leading indicators so the team can adapt before the reporting period ends.
Frequently asked questions
What is a revenue gap?
The difference between the revenue required and the revenue current commitments and credible opportunities are expected to produce.
Why can pipeline be misleading?
Totals can include weak, duplicated, delayed or poorly qualified opportunities.
Should every deal use the same probability?
No. Probability should reflect evidence and historical behaviour in comparable opportunities.
How often should the gap be reviewed?
Review at a cadence that leaves enough time to act, with more frequent checks in short sales cycles.
Put it into practice
Apply the framework to one current decision. Record the evidence, owner, next action and review date.
Download the complete carousel
Keep the five-slide framework as a PDF for your next working session.
International references
- Salesforce â Sales pipeline management
- Salesforce Trailhead â Opportunity management
- McKinsey & Company â The B2B customer decision journey
- McKinsey & Company â B2B omnichannel opportunity
- Christensen Institute â Jobs to Be Done Theory
- Strategyzer â Value Proposition Canvas
- Harvard Business Review â The discipline of business experimentation
- Harvard Business Review â Why organizations do not learn
- Google re:Work â Guide: Understand team effectiveness
- Atlassian â Roles and responsibilities
- Content Marketing Institute â Case study content
- Nielsen Norman Group â Recognition rather than recall